Paying for Precision: Auditing the Quality Customers Cannot See
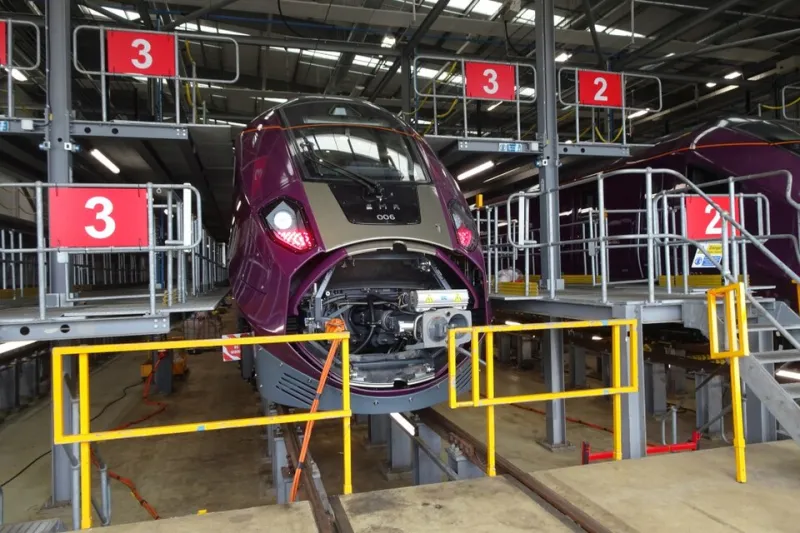
Photo: DS Pugh , CC BY-SA 2.0, via Wikimedia Commons
Most UK operations can point to a quality standard they are proud of. Fewer can explain which parts of that standard customers actually value. Between those two positions sits a quiet cost: inspection steps, approval layers, premium materials and reporting routines that add time and expense but do not change what the customer receives or is willing to pay for.
This is the over-specification tax. It is rarely introduced deliberately. It accumulates through good intentions, past incidents, regulatory caution and the natural preference of professionals for a margin of safety.
How over-specification accumulates
In service settings, the tax often appears as duplication. A low-value customer request passes through three approvals. A report is checked by two managers before a third decides not to read it. A service standard promises a response time that customers rarely need but that forces overtime every week.
In production, it appears as precision without a customer. A tolerance is tightened beyond what the product requires. A surface is polished where it will never be seen. Packaging is specified for a distribution journey the product no longer takes. Each decision may have been reasonable when it was made. The question is whether it remains reasonable now.
The tax is difficult to challenge because it hides inside phrases such as 'professional standard', 'customer expectation' or 'risk appetite'. Those phrases are not evidence. They are placeholders for a conversation that should have happened but did not.
Separate necessary quality from inherited habit
A useful audit begins with three questions for every specification, inspection or approval layer. First, can the customer see or feel the difference? Second, does the step prevent a material harm, regulatory breach or contractual failure? Third, what would happen if the step were removed for a controlled period?
If the answer to the first two questions is no, the specification is a candidate for challenge. That does not mean it is automatically wrong. It means it needs a reason beyond habit.
Necessary quality usually has a traceable link to customer value, legal obligation or material risk. Over-specification usually has a traceable link to an old complaint, an internal preference or a decision made when costs and service expectations were different. The audit should make that distinction visible without turning into a cost-cutting exercise.
A scoring method for challenging specifications
Score each specification on five dimensions from 0 to 3:
- Customer evidence: 0 means no evidence that customers notice or value it; 3 means customers consistently notice and value it.
- Harm avoidance: 0 means no credible link to safety, regulatory or contractual harm; 3 means removal would create a material risk.
- Obligation: 0 means no external requirement; 3 means a clear legal, regulatory or contractual requirement.
- Cost burden: 0 means negligible cost; 3 means significant direct cost or resource use.
- Delay burden: 0 means no meaningful slowdown; 3 means the step materially lengthens lead time or slows decisions.
Value score = customer evidence + harm avoidance + obligation. Burden score = cost burden + delay burden.
The decision rule is deliberately simple. Where value is 0–2 and burden is 4 or more, remove or trial removal. Where value is 3–5, test a simplified specification with customer and risk checks. Where value is 6 or more, retain the specification but review the evidence annually.
This method does not replace judgement. It disciplines the conversation. A high burden score does not prove a step is wasteful, and a high value score does not prove it is efficient. But the scoring makes assumptions visible, which is where improvement begins.
Removing the tax without eroding value
Removal should be staged, not sweeping. Start with specifications that have low customer evidence, low harm exposure and a clear burden. Run a controlled trial in one team, site or product line. Define in advance what evidence would show that quality has fallen: complaint rates, rework, returns, regulatory observations, customer satisfaction or sales conversion.
For service processes, the trial may mean removing a second approval for requests below a set value and monitoring error rates. For production, it may mean relaxing a tolerance within the customer's actual use case and checking performance in the field. The point is to test the specification against outcomes rather than defend it through opinion.
Where customer value is uncertain, ask customers directly. UK buyers are often pragmatic: they may value reliability and speed more than an invisible premium finish. A short research exercise can be more useful than another internal review meeting.
Removal should also leave a record. If a step is dropped, note the rationale, the evidence and the conditions under which it should be reinstated. That prevents the same specification from returning quietly after the next minor incident.
Make specification review routine
Over-specification is a governance issue, not merely an operational one. Specifications should have owners, review dates and change triggers: a new customer segment, a shift in regulation, a change in supplier or a sustained rise in cost. Strategy and operations leaders should see the value and burden scores together, because that is where trade-offs become explicit.
The aim is not to celebrate cheapness. It is to make quality deliberate. Customers should receive the standard they value, and the organisation should stop paying for precision that no one sees. An audit of invisible quality is therefore a strategy tool as much as an operational one: it aligns cost, speed and customer value around evidence rather than inherited habit.